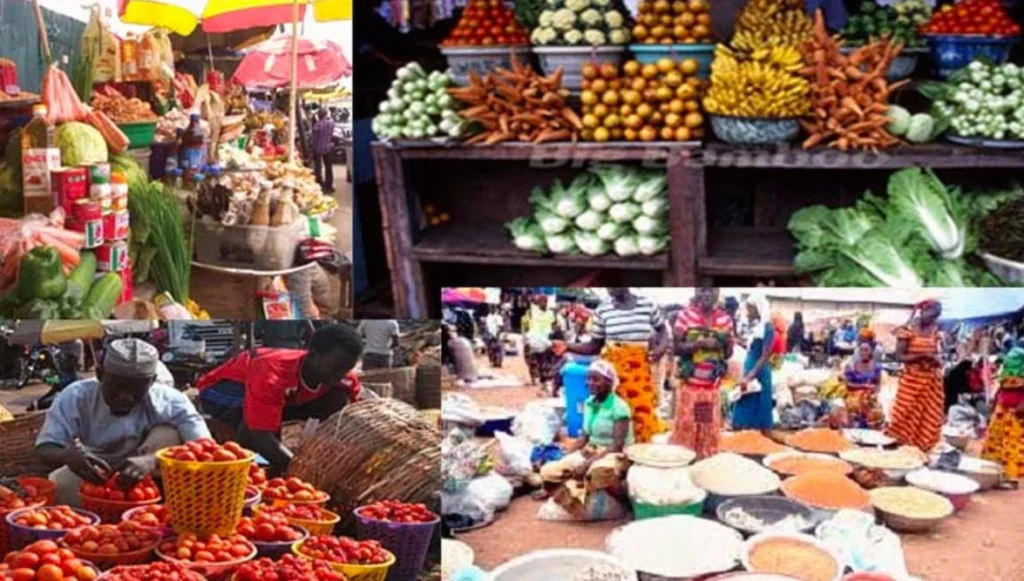
Nigerian households increasingly feel economic pressure not through debates over fiscal policy, but in open markets, supermarkets and neighbourhood stores where limited budgets must cover daily essentials. Even a modest rise in the cost of a regularly purchased item can force families to choose between competing needs.
That is why tax-compliance measures should be judged not only by the revenue they may deliver, but also by their effect on consumers’ spending power. Nigeria’s Excise Stamp Regulations, 2026, establish a combined physical and digital stamping and tracking system for excisable goods including alcohol, tobacco and sugar-sweetened drinks.
Quick facts
- The 2026 regulations cover excisable products such as alcoholic drinks, tobacco and sugar-sweetened beverages.
- The system is intended to improve traceability, verify product authenticity and curb illicit commerce.
- Manufacturers warn that compliance spending could increase production costs and ultimately retail prices.
- Key pressures already facing producers include energy costs, unreliable electricity, costly logistics and inflation.
The objectives of improving product tracing, authentication and enforcement against illegal trade are valid. However, the Manufacturers Association of Nigeria, or MAN, has cautioned that the cost of compliance may move through the supply chain and leave consumers paying more.
Regulatory costs do not vanish because they are initially imposed on manufacturers rather than charged directly to shoppers. Companies may have to fund machinery, technology, rollout programmes, employee training, product handling and other processes needed to meet the new rules.
Businesses could absorb part of those expenses, but they may also recover them through higher prices, reduced spending elsewhere, lower investment or changes to output. The effects will differ between products and companies, so it would be inaccurate to say every stamp-related cost will lead to a defined increase at retail level.
Still, policymakers should not assume compulsory compliance carries no consequences for consumers simply because the charge is not paid at the point of sale. MAN made that case in its September 2025 objection to the proposal, citing an already difficult business environment marked by high energy bills, poor power supply, expensive transport and inflationary strain.
The central question is not whether excisable goods should be regulated; they should be. The issue is whether the proposed approach is the least costly and most effective way to achieve that regulation.
If the Customs Service already holds digital records on production and excise activity, while tax authorities have e-invoicing data on commercial transactions, the government should identify exactly what extra information a physical stamp provides. Where stamps materially strengthen authentication or detection, that value should be quantified.
But if integrated digital identifiers and existing databases can generate the same information, the case for an added physical requirement becomes substantially weaker. Consumer welfare should be included in that evaluation from the outset, rather than considered only after prices have risen.
A policy can pursue a sound objective while still placing an excessive burden on the economy. A manufacturer required to alter a production line to apply new stamps may face costs beyond the stamps themselves.
If the adjustment slows output or requires more workers, a producer may need to redesign workflows, retain stock for longer periods or revise delivery schedules. Complex implementation could create delays and inefficiencies that affect both product availability and pricing.
Lower-income consumers may be hit hardest because their household budgets offer little protection against price increases. Retailers and distributors could also face higher operating costs if they must adopt new handling procedures or carry out product checks.
Consumer choice is another concern. If the price difference between legally produced goods and cheaper alternatives grows, buyers may reassess where and what they purchase.
MAN has warned that higher compliance expenses could steer price-sensitive consumers toward illicit products. That outcome is not inevitable, but it deserves close consideration in a country where smuggling and counterfeit goods remain major enforcement challenges.
If illegal products become more appealing because legitimate items cost more, the stamp programme could weaken its own purpose. The government could impose additional obligations on compliant companies while unlawful operators continue avoiding taxes and selling outside the formal economy.
Such an outcome would be inequitable: formal manufacturers would bear the compliance burden, households would encounter higher prices, and illicit traders could benefit from the wider price gap. Authorities must also separate policies that increase headline revenue from those that improve overall economic welfare.
A new regime might lift reported excise receipts from compliant firms while increasing their costs, reducing sales or encouraging consumers to move to untaxed goods. Gross collections alone therefore cannot determine whether the programme has succeeded.
A credible assessment should track the per-unit cost of compliance, movements in retail prices, shifts in production and sales, the share of products found to be illicit, and net revenue after implementation expenses. It should also establish whether price changes stem from the stamp system or from other influences, such as revised excise rates, energy prices, exchange-rate movements and distribution costs.
Without that evidence, both officials and opponents risk relying on assumptions. Industry concerns should not simply be rejected; they should be tested using transparent data.
Alternative options are available. The government could better link existing databases, expand risk-based audits, strengthen intelligence-led enforcement at borders and across domestic distribution channels, and introduce digital verification where clear gaps exist.
Those approaches should be measured objectively against the costs and benefits of the hybrid stamp framework. Where a physical stamp is truly needed for a particular product or high-risk supply chain, authorities should explain the reason, consider targeted use and allow adequate time for transition.
A broad, one-size-fits-all system should not proceed without determining whether the same results can be achieved more efficiently. Households should not be required to finance duplicate regulation.
Nigerian consumers cannot influence how agencies design administrative systems, arrange technology contracts or coordinate their data platforms. They should not become the default payers for an inefficient government structure.
Sound tax policy should be assessed not only by the revenue it raises, but by the efficiency of collection and its cost to the wider economy. If a stamp programme adds to household spending without a demonstrable improvement in enforcement, its social burden may exceed its public benefit.
The federal government should commission an independent assessment of consumer effects and publish clear evidence of the system’s added value. If the costs outweigh the gains, the regime should be revised or replaced by a more efficient option.
Nigeria needs a tax system that safeguards public revenue without needlessly increasing the cost of daily life. Authorities should pursue illicit operators, close enforcement weaknesses and collect taxes properly due, but ordinary consumers should not pay for a system whose necessity and benefits have yet to be convincingly established.