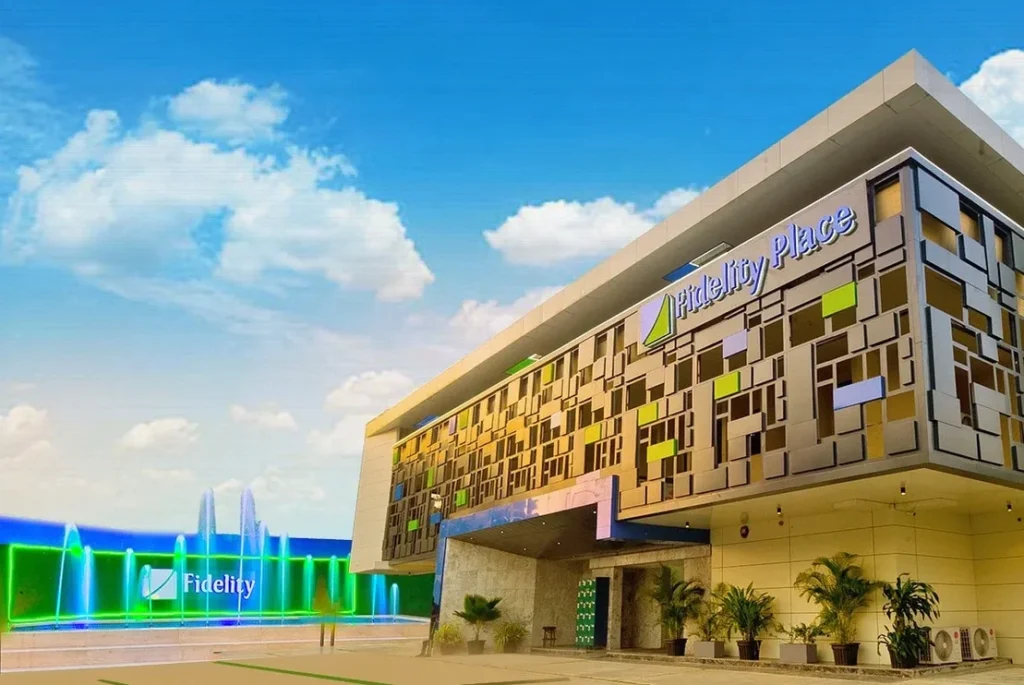
GCR Ratings has lifted Fidelity Bank Plc’s national-scale long-term issuer rating to A Plus (NG) from A (NG), while leaving its short-term rating at A1 (NG). The outlook is stable, with the upgrade driven mainly by a major improvement in the bank’s capital base.
Quick facts
- Additional core capital raised in 2025: NGN227.0 billion
- Core capital ratio: 29.4 percent in March 2026, up from 17.2 percent in December 2025
- Total assets: NGN10.5 trillion as of December 2025
- Estimated share of Nigeria’s gross banking loans: 8.0 percent
- Customer deposits: NGN7.4 trillion in March 2026
- Liquid assets covered wholesale funding 4.8 times
The rating decision follows the recognition of NGN227.0 billion in extra equity as part of Fidelity Bank’s core capital. GCR also pointed to the lender’s substantial position in Nigeria, dependable funding structure and solid liquidity as supporting factors.
Fidelity’s competitive standing remains a central credit strength. Its domestic franchise, built over almost 40 years, supports its position as the country’s sixth-largest bank, with NGN10.5 trillion in assets and an estimated 8.0 percent of industry gross loans at December 2025.
The lender intends to use its international banking licence to expand into three more African countries over the medium term. GCR expects that move to spread Fidelity’s geographic risk and improve its competitive position relative to other rated banks.
Fidelity raised NGN227.0 billion in new equity during 2025. The transaction allowed the bank to meet revised capital rules for its licence category, although the funds were formally counted as core capital in 2026.
That recognition pushed GCR’s measure of the bank’s core capital ratio to 29.4 percent at March 2026, from 17.2 percent three months earlier. Coverage of stage-three loan losses also remained above 100.0 percent.
GCR projects that the ratio will stay higher than 20.0 percent throughout the rating horizon, helped by the retention of a healthy portion of earnings. It also said the bank’s oil and gas exposure is spread across upstream, downstream and service activities, while natural hedges help limit foreign-exchange risk.
Fidelity’s funding position is supported by a broad and stable deposit franchise. Customer deposits increased 16.1 percent in the year to December 2025 and then rose another 7.1 percent by March 2026, reaching NGN7.4 trillion.
Deposits represented 89.5 percent of total funding at March 2026. Around 90 percent came from current and savings accounts, which generally carry lower costs and provide a durable funding base.
The bank also retained a strong liquidity cushion through its sizeable holdings of liquid assets. Liquid assets equalled 56.9 percent of customer deposits in March 2026 and covered wholesale funding 4.8 times.
The stable outlook assumes Fidelity will preserve its sound financial profile. That view depends on core capital staying above 20.0 percent, alongside steady funding, ample liquidity and resilient asset-quality measures.